


We are committed to delivering exceptional service while embracing the future of wealth planning.


Why Choose Hoxton Wealth For Investing?
In an ever-evolving financial world, it is difficult to know what is noise and what needs to be acted upon. At Hoxton Wealth, we integrate our unique technology with expert insights to provide a seamless, efficient, and personalised investment experience.
1Technological Integration
The Hoxton Wealth App, allows for real-time monitoring of your portfolio where ever you are. You can seamlessly look at all of your portfolios globally in one place and understand how they are performing.
2Investment Strategies For You
Our highly trained wealth planners will work with you to ensure that your portfolio, your goals, objectives and risk appetite are all taken into account when designing a portfolio that is optimal to you.
3Global Reach
With clients located all over the globe, we realise that one size does not fit all. We therefore construct our portfolios and have different currencies dependent on where our clients reside.
4Value Fee Structure
We believe that your portfolio should be well structured and offer you great value for money. Fees play an important part in how your portfolio grows overtime and it is therefore important to ensure they are reasonable. Our portfolios start from as little as 0.5% for a fully global indexed based solution.
5Expert Team
Our team includes seasoned financial experts with deep industry knowledge and a commitment to continuous learning and adaptation in the fast-paced financial environment.


Investment Advice Starts With Purpose
Before asking what to invest in, it helps to answer a more important question:
- What is the money for?
- You may be investing to:
- build long-term wealth
- prepare for retirement
- generate future income
- preserve accumulated capital
- provide financial flexibility
- fund future family commitments
- invest an inheritance
- manage proceeds from a business sale
- support future generations
- bring investments accumulated internationally into one strategy
Different objectives can require different approaches.
Money intended for a major purchase in three years has a different purpose from capital intended to support retirement several decades from now.
The investment strategy should reflect that distinction.
See Your Investments as One Portfolio
As wealth accumulates, it is common for investments to become spread across different providers and accounts.
An international career can make that fragmentation more pronounced.
You might have:
- an investment portfolio in your current country
- older investments retained abroad
- pensions with underlying investment exposure
- company shares
- cash in several currencies
- property
- investment accounts established at different stages of your life
- portfolios managed by different institutions
Looking at each arrangement separately can make it difficult to understand your overall position.
Two individual portfolios may each appear diversified while producing significant concentration when combined.
A coordinated review can help you understand what you own, where your investment risk sits and whether the different parts of your wealth are working towards the same objectives.
A Planning-Led Approach to Investing
Investment recommendations should sit within your wider financial plan.
That means considering more than potential returns.
Relevant questions can include:
- What are your objectives?
- When might you need the money?
- How much investment risk are you comfortable taking?
- How much loss could your wider financial position withstand?
- What other investments and assets do you already hold?
- What liquidity might you need?
- Where are you likely to live in future?
- Which currencies are relevant to your spending?
- Are there tax or regulatory considerations linked to your country of residence?
- Do you have sustainability preferences that should be reflected?
- How will the portfolio be reviewed over time?
Only once these questions are understood does portfolio construction have the right context.
Understanding Investment Risk
Investment risk cannot be reduced to a single label.
A useful assessment needs to consider several aspects of your circumstances.
Your Attitude to Risk
How comfortable are you with fluctuations in the value of your investments?
Some investors can tolerate substantial short-term falls without changing course. Others may find the same experience difficult, even where the long-term objective has not changed.
Your Capacity for Loss
Being emotionally comfortable with risk is different from being financially able to absorb losses.
A significant market decline could have very different consequences for someone who is decades from needing their money than for someone who depends on the portfolio to fund near-term expenditure.
Your Investment Timeframe
The time available before capital is required can affect the amount and type of investment risk that may be appropriate.
Your Objectives
Risk only makes sense in relation to what the portfolio is intended to achieve.
Your Wider Financial Position
Pensions, property, business interests, cash and other investments can all affect the amount and type of risk within your overall wealth.
Under the MiFID II suitability framework, firms providing investment advice or portfolio management must obtain information about matters including a client's knowledge and experience, financial situation including ability to bear losses, and investment objectives including risk tolerance, so that suitable services and financial instruments can be recommended.


Diversification
Diversification is an important part of portfolio construction.
Rather than relying excessively on one company, sector, country or investment type, a diversified strategy can spread exposure across different sources of risk and return.
Depending on the portfolio, diversification may involve different:
- asset classes
- geographic markets
- industries
- companies
- investment styles
- fund managers
- currencies
- types of fixed-income exposure
Diversification does not remove investment risk and does not prevent losses.
Its purpose is to avoid unnecessary dependence on a narrow part of the market and build a portfolio whose overall characteristics are better aligned with your objectives.
The right level and type of diversification still depend on your individual circumstances.
Your Investment Timeframe Matters
Not all of your wealth necessarily has the same investment horizon.
You may need some capital within the next few years while another part of your portfolio is intended to support retirement much later.
Treating both amounts identically can ignore the different jobs they need to perform.
Shorter-term needs may require greater consideration of liquidity and the consequences of a market fall shortly before the money is required.
Longer-term capital may have more time to experience periods of market volatility, although a longer timeframe does not remove investment risk.
Connecting investments to future financial needs can give individual parts of your wealth a clearer purpose.
Investment Portfolio Management
Building an investment strategy is only the beginning.
Markets move. Asset values change. Your circumstances evolve. A portfolio that was aligned with its intended strategy when first constructed can develop differently over time.
Ongoing portfolio management can involve:
- implementing an agreed investment strategy
- monitoring the portfolio
- reviewing asset allocation
- assessing risk
- considering diversification
- rebalancing where appropriate
- reviewing costs
- reporting
- considering changes in your circumstances or objectives
The purpose of ongoing management is not to react to every market headline.
It is to maintain disciplined oversight and keep the portfolio connected to the strategy it is intended to follow.
International Investment Portfolios
Internationally mobile investors need to consider more than where attractive investments may be found.
Where you live can affect the practical and financial context around the portfolio.
An investment arrangement established while living in one country may need to be reconsidered after moving elsewhere.
Questions can include:
- Can the existing provider continue to service you?
- Is the account or product appropriate for your current residence?
- Where are the assets held?
- What currencies are involved?
- How does the portfolio fit with future spending?
- Are there relevant tax consequences?
- Are there local reporting requirements?
- What happens if you move again?
The answers depend on the investment and the jurisdictions involved.
That is why an international portfolio should be reviewed as part of the wider cross-border financial plan rather than judged purely on investment performance.
Investing Across Different Currencies
Currency can matter when the money you own and the money you eventually spend are denominated differently.
You might earn in euros, hold investments in sterling and expect to retire somewhere where your expenditure is primarily in another currency.
Exchange-rate movements can affect what overseas assets are worth in terms of your future spending.
But currency exposure is not automatically something that should be eliminated.
International investments naturally create exposure to different currencies, and the appropriate approach depends on your objectives, future liabilities, investment timeframe and wider financial position.
The first step is to understand the exposure you already have.
Investment Advice After Moving Country
Relocating does not automatically mean an existing portfolio is inappropriate.
It does mean the context has changed.
Your new residence can affect:
- the tax treatment of investments
- which products or accounts can be serviced
- regulatory considerations
- reporting requirements
- the currencies relevant to your finances
- your future spending needs
- the role of existing tax wrappers
- estate-planning considerations
Before selling, transferring or reorganising investments, it is important to understand the existing arrangements and what a proposed change would mean.
Where specialist tax advice is required, it should be provided by an appropriately qualified professional familiar with the relevant jurisdictions.
Sustainable and Responsible Investing
Investment preferences are not limited to risk and return.
Some investors also want environmental, social or other sustainability considerations reflected in the way their wealth is invested.
Those preferences need to be understood clearly.
They should then be considered alongside the other elements of a suitable investment strategy, including objectives, risk, timeframe, diversification and liquidity.
Under the EU's MiFID II suitability framework, sustainability preferences form part of the suitability process where relevant to the client. ESMA's suitability guidance incorporates the assessment of those preferences into investment advice and portfolio management.
Sustainable preferences therefore form one part of the wider investment discussion rather than replacing investment discipline.
Private Markets and Alternative Investments
For some high-net-worth and sophisticated investors, a wider portfolio may include investments beyond traditional listed equities and bonds.
Private markets and other alternative investments can have different characteristics from publicly traded assets.
Depending on the investment, considerations may include:
- liquidity
- investment timeframe
- valuation
- complexity
- fees and expenses
- concentration
- access to capital
- manager selection
- underlying investment risk
The fact that an investment is less accessible or more complex does not itself make it suitable.
Its role needs to be considered within the complete portfolio and the investor's ability to understand and bear the associated risks.
Understanding Investment Costs
Investment returns are only one side of the equation.
Costs also affect what investors retain.
Depending on the arrangement, costs can arise at different levels, including investment management, underlying funds, platforms or custody, transactions and advice.
The relevant charges depend on the portfolio and services involved.
For retail investment products within the scope of the EU PRIIPs framework, a Key Information Document is intended to provide prescribed pre-contractual information including information about risk, potential performance scenarios and costs.
A portfolio review should therefore look beyond headline performance and consider the costs associated with the overall strategy.
Avoid Letting Headlines Become Your Strategy
Investment markets generate a constant flow of information.
Interest rates change. Elections take place. Markets rise and fall. New technologies attract attention. Economic forecasts are revised.
Some developments matter.
But repeatedly changing a long-term portfolio in response to short-term headlines can pull the investment strategy away from the objective it was designed to support.
A disciplined process provides a framework for deciding when a change is justified and when staying with the existing strategy may be more appropriate.
The question is not simply:
"What are markets doing today?"
It is:
"Has anything changed that means this portfolio is no longer appropriate for what I need it to do?"
Reviewing an Existing Portfolio
You do not necessarily need to replace an investment portfolio to improve your financial planning.
The first step may simply be to understand what you already own.
A portfolio review can consider:
- current holdings
- asset allocation
- investment risk
- concentration
- diversification
- costs
- liquidity
- currency exposure
- alignment with your objectives
- how the portfolio fits alongside pensions and other assets
- whether your circumstances have changed since the investments were selected
For international clients, the review can also identify investments that deserve closer examination because residence or future relocation has changed.
The outcome should not be predetermined.
Some investments may remain appropriate. Others may need further review.
Investing Towards Retirement
As retirement approaches, the purpose of a portfolio can begin to change.
During the accumulation years, the emphasis may be on building capital over the long term.
Closer to retirement, other questions become more important.
- How much will you need to withdraw?
- Which assets will provide income?
- How much liquidity should you maintain?
- What happens if markets fall early in retirement?
- Which currencies will you spend in?
- How do pensions fit alongside the portfolio?
Investment strategy therefore needs to remain connected to retirement planning rather than operating as a separate exercise.
Investment Governance
A well-constructed portfolio needs a clear decision-making framework.
That means being able to explain:
- what the portfolio is trying to achieve
- what level of risk it is intended to take
- how it is diversified
- why particular types of investments are included
- how costs are considered
- how performance is assessed
- when the portfolio is reviewed
- what could justify a change
For investors with significant wealth, governance can become increasingly important as the number of assets, accounts and decision-makers grows.
A clear structure helps distinguish deliberate investment decisions from changes driven by short-term market noise.
How Our Investment Planning Process Works
We establish what the capital is intended to achieve and how it fits within your wider financial plan.
We consider the investments and other assets you already hold, including arrangements held across different countries where relevant.
Your attitude to risk, capacity for loss, timeframe, objectives and wider circumstances are considered.
An appropriate asset allocation and investment approach can then be considered within the relevant regulatory framework.
For internationally mobile clients, residence, product availability, currency, custody, tax awareness and future relocation may need to be taken into account.
Where specialist tax advice is needed, this should be coordinated with an appropriately qualified professional.
Once recommendations have been explained and agreed, the investment strategy can be implemented.
The portfolio and the financial plan should be reviewed as circumstances and objectives change.
International Investing Guide
Investing internationally can raise questions that go beyond asset selection.
Our International Investing Guide is designed to help you consider areas such as:
- investment objectives
- risk
- diversification
- portfolio structure
- currency
- international accounts
- moving country
- tax awareness
- retirement planning
- reviewing investments held in several jurisdictions
It provides a structured starting point for understanding the issues before making significant investment decisions.
FAQs
An investment adviser helps assess your circumstances and objectives before recommending an investment strategy or investments that are appropriate within the relevant regulatory framework.
That can involve understanding your objectives, timeframe, financial position, ability to bear losses, risk tolerance and existing investments.
For international clients, other factors such as residence, currency and existing overseas portfolios may also need to be considered.
There is no universal portfolio value at which investment advice becomes appropriate.
The usefulness of advice depends on your circumstances, the decisions you face and the complexity of your financial position.
Advice can become particularly relevant when substantial wealth is spread across several portfolios, pensions, countries or currencies, or when the money needs to support significant future objectives such as retirement.
Investment advice involves personal recommendations about investments based on your circumstances.
Portfolio management generally involves ongoing management of investments in accordance with an agreed mandate or strategy.
The exact service and regulatory arrangements depend on the provider and agreement involved.
Both should remain connected to your wider financial objectives.
Risk assessment goes beyond asking whether you consider yourself cautious or adventurous.
It can include your attitude to investment risk, financial capacity to bear losses, investment objectives, timeframe and wider circumstances.
Under MiFID II, suitability assessments for investment advice and portfolio management include relevant information about the client's knowledge and experience, financial situation including ability to bear losses, and investment objectives including risk tolerance.
No.
Diversification can reduce reliance on individual investments or parts of the market, but it cannot remove investment risk or guarantee against losses.
Its purpose is to spread exposure more deliberately across different investments whose risks and return drivers may differ.
Not automatically.
A move can change the tax, regulatory, practical and currency context around existing investments, but that does not by itself mean they should be sold or transferred.
The existing arrangements and any proposed alternatives should be reviewed before changes are made.
Possibly, but it depends on the investment, provider, your country of residence and the relevant legal and regulatory requirements.
Some providers may have restrictions on servicing clients resident in particular jurisdictions. Tax treatment and reporting can also differ.
The position should therefore be checked for the specific investments involved rather than assumed.
Not necessarily.
The currencies relevant to an investment strategy can depend on where you expect to spend the money, your other assets and liabilities, investment timeframe and the underlying investments themselves.
Living in a eurozone country, for example, does not automatically mean every investment should be denominated in euros.
Yes.
Where relevant, sustainability preferences can be considered alongside your financial objectives, risk profile, timeframe and other suitability factors.
Under the EU MiFID II suitability framework, sustainability preferences have been incorporated into the suitability assessment for investment advice and portfolio management.
No.
Private-market and alternative investments can involve characteristics such as limited liquidity, longer investment periods, greater complexity and different valuation arrangements.
Their suitability depends on the investor, the specific investment and the role it is expected to play within the wider portfolio.
There is no single review interval appropriate for every investor.
A portfolio should be reconsidered when relevant circumstances or objectives change. Ongoing advice or portfolio-management arrangements may also provide for periodic reviews.
A move country, retirement, significant withdrawal, inheritance, business sale or substantial change in financial circumstances can all justify reviewing the investment strategy.
Recent performance is one piece of information, but it does not tell you whether a portfolio remains appropriate.
A more useful review considers performance alongside risk, objectives, timeframe, diversification, costs and the role the portfolio plays within your wider financial plan.
Invest With a Clearer Purpose
An investment portfolio should not exist independently from the rest of your financial life.
It should have a purpose, an appropriate level of risk and a clear role within your wider wealth.
For internationally mobile investors, it should also recognise the countries, currencies and future plans that can affect how the portfolio is used.
Hoxton Wealth helps clients bring those factors together, build a more structured investment strategy and review it as circumstances change.
Financial clarity. Delivered by people, enabled by technology.
The Hoxton Wealth App: Your Investment Companion




Comprehensive Dashboard
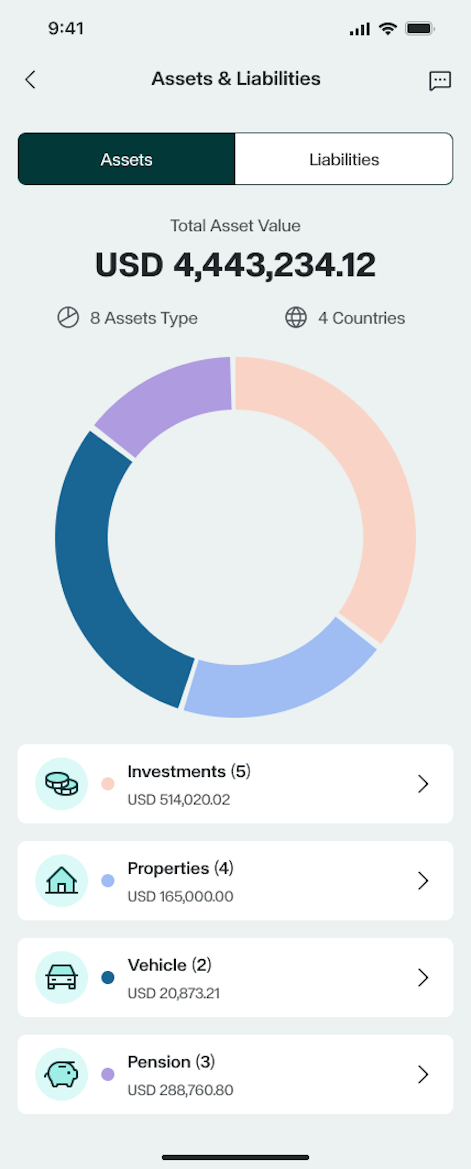
View all your investments in one place with our intuitive dashboard. Monitor performance, track asset allocation, and stay updated with real-time data.
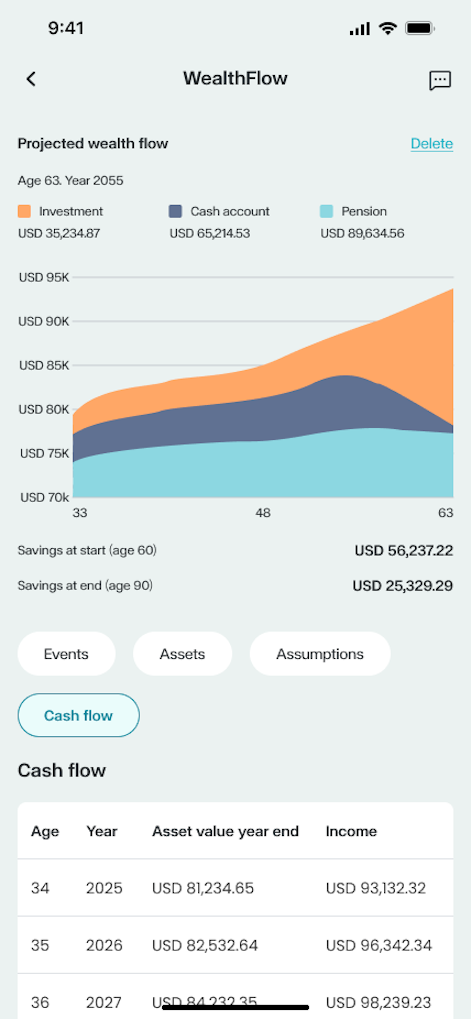
WealthFlow
Our innovative WealthFlow feature offers a holistic view of your financial health by allowing you to connect and synchronise your bank accounts and investment accounts. This integration enables seamless tracking of your finances and better financial planning.
Goal Tracking
Set and track your financial goals within the app, receiving regular updates and insights to help you stay on course.
Live Net worth Tracker
Keep an eye on your overall financial health with our live net worth tracker, which aggregates data from all your accounts to offer an up-to-date view of your net worth.
Secure Document Storage
Store important financial documents securely in the app, ensuring you have access to them whenever needed.
Alerts and Notifications
Stay informed with custom alerts and notifications on market movements, portfolio changes, and investment opportunities.

