


With our years of financial planning experience, we at Hoxton Wealth are committed to helping you develop your future, focusing on what’s important for you and guiding you to make informed financial decisions.


Start With the Purpose of Your Capital
One part of your wealth may be intended to support retirement over several decades. Another may be needed for a property purchase within a few years. You may want to preserve liquidity for family commitments or retain capital for future opportunities.
Those objectives can require different approaches.
Before making an investment recommendation, it is important to understand:
- what the money is intended to achieve
- when you may need access to it
- how much investment risk is appropriate
- your existing investments and other assets
- your expected future income
- your ability to bear investment losses
- relevant investment preferences
This is central to regulated investment advice.
Under MiFID II, firms providing investment advice must obtain the information necessary to recommend financial instruments that are suitable for the client, including information about their financial situation, ability to bear losses, investment objectives, and risk tolerance.
The portfolio follows the objective, not the other way around.
Explore Investment Advice
1Investment Advice Is More Than Selecting Investments
Individual funds and securities matter.
So does the structure around them.
An investment strategy can involve decisions about:
- asset allocation
- diversification
- portfolio risk
- investment timeframe
- liquidity
- currency exposure
- investment preferences
- existing holdings
- portfolio costs
- ongoing review
For an internationally mobile client, the practical position may also depend on where they live and where an investment arrangement is held.
The aim is to bring these factors into a coherent investment strategy rather than assess individual investments without the wider context.
2Understanding Your Existing Investments
Many clients come to investment advice with substantial portfolios already in place.
Those investments may have accumulated through different stages of life.
You might have:
- an investment account established years ago
- portfolios with several providers
- holdings from a previous country of residence
- investments linked to former employment
- substantial cash balances
- inherited investments
- concentrated company shares
- investments accumulated alongside a business
- retirement assets with investment components
The starting assumption should not be that everything needs to change.
An existing arrangement may remain appropriate.
Others may no longer reflect your objectives, current residence, risk profile or wider financial position.
A structured review can establish what you own, why you own it and whether it still has a clear role.
3Building an Investment Strategy
An investment strategy provides the framework for individual portfolio decisions.
It begins with your objectives and constraints.
That can include:
- required investment timeframe
- expected withdrawals
- liquidity needs
- capacity for loss
- attitude to investment risk
- existing assets
- income requirements
- relevant currencies
- investment preferences
The resulting strategy may then determine how capital is allocated across appropriate investments.
There is no universal portfolio for an affluent investor.
Two people with similar levels of wealth can reasonably have different investment strategies because the purpose of their capital, financial circumstances and tolerance for risk are different.
4Risk Needs to Be Understood in Context
Investment risk is not simply a number on a questionnaire.
Several questions matter.
- How comfortable are you with market fluctuations?
- How much financial loss could your wider position withstand?
- When will you need the capital?
- Would a significant fall affect an important future objective?
- How much of your wealth is already exposed to other risks, such as a business, employer shares or property?
MiFID II requires investment firms providing investment advice to consider a client's risk tolerance and ability to bear losses as part of the suitability assessment.
Those are related, but they are not identical.
You may be emotionally comfortable with substantial investment volatility while having limited financial capacity to absorb it.
Equally, you may have considerable financial capacity for loss while preferring a more measured investment approach.
Both matter.
Explore Investment Risk Profiling


Diversification
Concentration can build quietly.
A successful career may leave you with substantial shares in one employer.
A business owner may have much of their net worth tied to one company.
Property can represent a large proportion of family wealth.
Several investment funds can appear diversified while holding many of the same underlying companies.
Diversification aims to avoid unnecessary dependence on a single investment, market, sector or source of return.
It does not remove investment risk, and a diversified portfolio can still fall in value.
The appropriate level and form of diversification depend on your wider circumstances and the role of the portfolio.
1International Investment Portfolios
Internationally mobile investors can face additional practical questions.
You may live in one EU/EEA country while holding investments established elsewhere.
Your future spending may be in a different currency from much of your existing wealth.
You may also expect to relocate again.
That can make it useful to consider:
- current residence
- future residence plans
- provider servicing restrictions
- portfolio currency exposure
- investment portability
- access to capital
- existing account structures
- the jurisdiction in which an arrangement is held
Tax treatment and reporting requirements can also be relevant to international investment decisions, but these depend on individual circumstances and jurisdiction.
Hoxton Capital Management (Europe) Ltd does not provide tax advice. Where taxation may materially affect a decision, an appropriately qualified tax adviser should assess the position.
Explore Investment Risk Profiling


Investment Advice When You Move Country
Relocation is a sensible point to review an investment portfolio.
It is not automatically a reason to change it.
An investment that was established while you lived in another country may still be appropriate. Equally, a change in residence can alter the practical context around an account or provider.
Questions can include:
- Can the existing provider continue to service you?
- Does the portfolio still reflect your objectives?
- Has the currency of your future spending changed?
- Do you expect another move?
- Does the investment remain suitable for your timeframe and risk profile?
- Are there local tax questions requiring separate specialist advice?
Changing investments can have consequences of its own.
A review should therefore come before a decision to retain, restructure or replace an existing arrangement.


Currency and Your Investments
International investors frequently hold assets and future liabilities in different currencies.
For example, you may hold investments denominated in sterling while expecting to fund retirement spending in euros.
Currency movements can affect the value of those investments when measured against your future spending needs.
That does not mean all foreign-currency exposure should be removed.
Currency exposure can arise through:
- the currency in which an investment is priced
- the underlying assets owned by a fund
- overseas income
- future expenditure
- property
- pensions and other financial assets
The relevant question is how currency exposure affects your investment objectives and wider financial position.
This is an investment-planning consideration, not a standalone foreign-exchange management service.


Investing for Retirement
Retirement often changes the role of an investment portfolio.
During your working life, you may be adding capital regularly and have limited need for withdrawals.
Later, investments may need to help support expenditure.
That can make questions around risk, liquidity and withdrawal strategy more important.
Investment planning for retirement can consider:
- expected spending
- other sources of retirement income
- pension assets
- investment timeframe
- liquidity
- capacity for loss
- expected withdrawals
- portfolio risk
Retirement planning may also involve pension, tax and estate considerations beyond investment advice.
Where specialist tax or legal advice is required, it should be provided separately by appropriately qualified professionals.


Pensions and Investment Advice
Pensions can represent a significant part of an investor's long-term assets.
They can also involve more than investment selection.
Existing pension arrangements may contain:
- particular benefits
- guarantees
- access rules
- investment choices
- charges
- death benefits
- transfer restrictions
For clients who have worked internationally, pensions may also have been accumulated in several countries.
The objective should not be to transfer or consolidate pensions simply for administrative convenience.
Where pension advice falls within the relevant service and permissions, the existing arrangement and available options need to be considered carefully before a recommendation is made.
Some pension matters may require additional specialist advice or fall outside the services available through HCM EU.


Sustainable Investment Preferences
Some investors want environmental, social or governance considerations reflected in their investments.
Those preferences can form part of the investment-advice process where relevant.
They still need to be considered alongside:
- financial objectives
- risk
- diversification
- timeframe
- liquidity
- product characteristics
Sustainable or responsible investing does not remove investment risk, and labels can encompass different approaches.
Understanding what a particular investor means by sustainability is therefore important before considering suitable investments.


Private Markets and Alternative Investments
Some investors may consider investments outside conventional listed equities and bonds.
Depending on the instrument, these can introduce characteristics such as:
- limited liquidity
- longer holding periods
- more complex valuation
- different fee structures
- higher minimum commitments
- additional investment risk
- restricted eligibility or target markets
They are not appropriate for every investor.
Any consideration of private-market or alternative investments should remain within HCM EU's permitted financial instruments and approved target market.
Suitability, liquidity and the role of the investment within the overall portfolio need particular attention.
Explore Private Markets and Alternative Investment Considerations


Investment Planning Around a Business
Business owners often accumulate wealth differently from salaried professionals.
A substantial proportion of net worth may remain tied to the company.
That can mean personal financial exposure is concentrated in:
- one business
- one industry
- one economic environment
- one source of income
Investment planning can consider the assets held outside the company and what role they need to play in the owner's wider financial position.
An eventual business sale can create another significant change, as concentrated private-company wealth becomes liquid personal capital.
Corporate finance, business-sale structuring, company law and tax advice are separate specialist areas and are not presented as HCM EU investment-advice services.


Investing After a Liquidity Event
A business sale, inheritance, property disposal or other significant event can create a substantial amount of investable capital.
There is no requirement to invest everything immediately.
Before deciding how the capital should be invested, it can be useful to separate:
- immediate spending
- known liabilities
- cash reserves
- capital required within the next few years
- longer-term investment capital
The appropriate strategy depends on what the money needs to achieve.
A large cash balance can feel like a single investment decision.
In practice, different parts of that capital may have very different purposes and timeframes.


Tax Considerations and Investment Decisions
Tax can affect the outcome of investment decisions.
But HCM EU does not provide tax advice.
This distinction is important.
Investment advice may identify that tax could be relevant to a proposed action, for example when considering the disposal of an existing investment or a change following relocation.
The tax consequences themselves should be assessed by an appropriately qualified tax adviser where required.
Investment recommendations can then take relevant specialist tax advice into account without presenting HCM EU as the provider of that tax advice.


Estate and Succession Considerations
Investments can form part of an individual's eventual estate.
Ownership, beneficiaries, family circumstances and cross-border connections may therefore be relevant to the wider financial context.
HCM EU does not provide legal, will-writing or trust services.
Where succession law, wills, powers of attorney, trusts or other legal matters need to be addressed, advice should be obtained from an appropriately qualified legal professional.
The investment-advice role is narrower: to understand relevant client circumstances where they affect investment objectives and recommendations.


Property and the Investment Picture
Property and financial investments often sit on the same personal balance sheet.
A client with substantial property exposure may have different diversification and liquidity considerations from someone whose wealth is predominantly held in financial assets.
Property can affect:
- overall concentration
- liquidity
- borrowing
- future capital requirements
- retirement plans
- currency exposure
HCM EU does not provide general property, conveyancing or property-tax advice through its investment-advice service.
The relevant question is how existing or planned property ownership affects the financial and investment position.


Ongoing Investment Advice
An investment portfolio is established at a particular point in time.
Your life does not remain there.
Over time, you may:
- retire
- move country
- sell a business
- receive an inheritance
- buy or sell property
- change career
- support family
- alter your spending plans
- change your investment preferences
Markets and investment conditions also change.
Ongoing advice provides an opportunity to review whether the portfolio remains suitable for your circumstances and objectives.
That does not mean making frequent changes.
Sometimes the appropriate conclusion after a review is that the existing strategy remains suitable.


Avoiding Unnecessary Investment Activity
A good investment process does not require constant action.
Periods of market volatility can make changing strategy feel urgent.
So can news, short-term performance or the recent success of a particular asset.
But investment decisions should remain connected to the purpose and timeframe of the portfolio.
Before making a material change, useful questions include:
- Has my objective changed?
- Has my timeframe changed?
- Has my capacity for loss changed?
- Has my need for liquidity changed?
- Has my personal situation changed?
- Has the investment ceased to be suitable for its intended role?
If the answer is no, short-term market movement alone may not justify changing a long-term strategy.
How Investment Advice Can Work
1. Understand Your Circumstances
We begin with your objectives, financial position, existing investments, timeframe, and relevant personal circumstances.
2. Establish Your Investment Objectives
We identify what the capital needs to achieve and when it may be required.
3. Assess Risk and Capacity for Loss
Your attitude to risk and financial ability to withstand losses are considered as part of suitability.
4. Review Existing Arrangements
Where you already hold investments, their role, characteristics, and suitability can be assessed before changes are considered.
5. Develop the Investment Recommendation
Appropriate investments can be considered in the context of your objectives, risk profile, and wider circumstances.
6. Identify External Specialist Issues
Where tax, legal, or other matters sit outside HCM EU's service scope, the need for appropriately qualified specialist advice can be identified.
7. Implement Agreed Recommendations
Where you decide to proceed, recommendations can be implemented within the applicable regulatory permissions and service arrangements.
8. Review Over Time
Where ongoing advice is provided, the strategy can be reviewed as your circumstances and objectives evolve.
FAQs
Investment advice involves making personal recommendations about investments based on relevant information about your circumstances.
Depending on the service and your needs, this can include reviewing existing investments, establishing objectives, assessing risk and capacity for loss, considering asset allocation and recommending suitable financial instruments.
The precise scope depends on the service available and applicable regulatory permissions.
EU002 is the high-level gateway to HCM EU's investment-advice services. It helps visitors understand the different circumstances in which investment advice may be relevant and routes them towards more specific investment, pension, retirement and cross-border content.
EU012 is the dedicated Investment Advice pillar and goes deeper into the investment-advice process, portfolio construction, suitability and ongoing advice.
Not necessarily.
Investment advice involves personal recommendations to a client.
Discretionary portfolio management involves making investment decisions on behalf of a client within an agreed mandate.
The amended EU page architecture deliberately uses Investment Portfolio Advice rather than Investment Portfolio Management for EU013 to avoid suggesting that HCM EU provides a discretionary portfolio-management service where that is not the service being described.
Under MiFID II, investment firms providing investment advice must obtain information necessary to assess suitability.
Relevant areas include the client's knowledge and experience, financial situation, ability to bear losses, investment objectives and risk tolerance.
The specific recommendation should reflect the client's individual circumstances rather than a generic investor profile.
Not necessarily.
Existing investments should be understood before changes are recommended.
Some may remain suitable and continue to serve a clear purpose.
Others may no longer fit your objectives, risk profile, liquidity requirements or current circumstances.
A review establishes the position before deciding whether action is appropriate.
Cross-border circumstances can be considered as part of investment advice where the service can lawfully be provided to the client.
Residence, provider restrictions, currency exposure and existing arrangements may all be relevant.
Tax and legal questions arising from different jurisdictions require appropriately qualified specialists where they fall outside HCM EU's service scope.
No.
The compliance review expressly states that HCM EU does not provide tax advice. Tax-related pages are therefore being positioned as educational information or tax considerations relevant to investment planning rather than HCM EU tax-advice services.
Where a tax question could materially affect an investment decision, clients should obtain advice from an appropriately qualified tax adviser.
HCM EU does not provide legal, will-writing or trust services.
Legal and succession issues can be relevant to a client's wider circumstances, but specialist legal advice should be obtained from an appropriately qualified professional. The revised EU architecture specifically requires estate and succession pages to remain educational rather than being presented as HCM EU legal services.
The revised architecture does not present general property advice as an HCM EU service.
Property can still be relevant to investment planning because it affects areas such as liquidity, concentration, borrowing and the wider balance sheet.
Detailed property, legal and tax matters require the appropriate specialist advisers.
The Insurance and Wealth Protection service is currently on hold pending confirmation of the relevant insurance-distribution permissions, responsible entity and distribution arrangements.
It should therefore not be presented as an HCM EU service unless those matters are confirmed.
Investments can form an important part of retirement planning.
Advice can consider the purpose of invested capital, expected withdrawals, timeframe, liquidity and appropriate investment risk.
Pension, tax and legal matters can involve separate considerations and may require additional or specialist advice.
A move can justify reviewing existing investments, but it does not automatically mean they need to be changed.
Provider servicing, investment suitability, currency and other practical issues may need consideration.
Tax consequences depend on the jurisdictions and individual circumstances and should be assessed by an appropriately qualified tax adviser.
Only investments falling within the relevant HCM EU permissions and approved target market should be presented as available for advice.
The compliance review has specifically placed the Private Markets and Alternative Investments page on hold pending confirmation that all products intended to be covered fall within HCM EU's permitted financial instruments and approved target market.
The appropriate frequency depends on the advice arrangement and individual circumstances.
A review can also be particularly important after a significant change such as retirement, relocation, a business sale, inheritance or material change in objectives.
A review does not necessarily mean the portfolio needs to change.
The Hoxton Wealth App: Your Financial Planning Companion


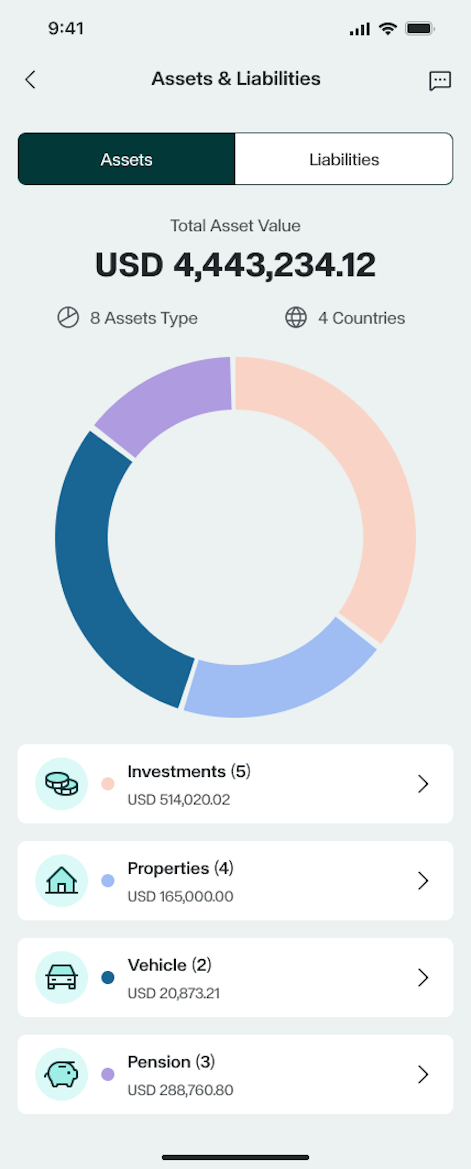


Comprehensive Dashboard
View all your financial plans in one place with our intuitive dashboard. Monitor performance, track progress, and stay updated with real-time data.
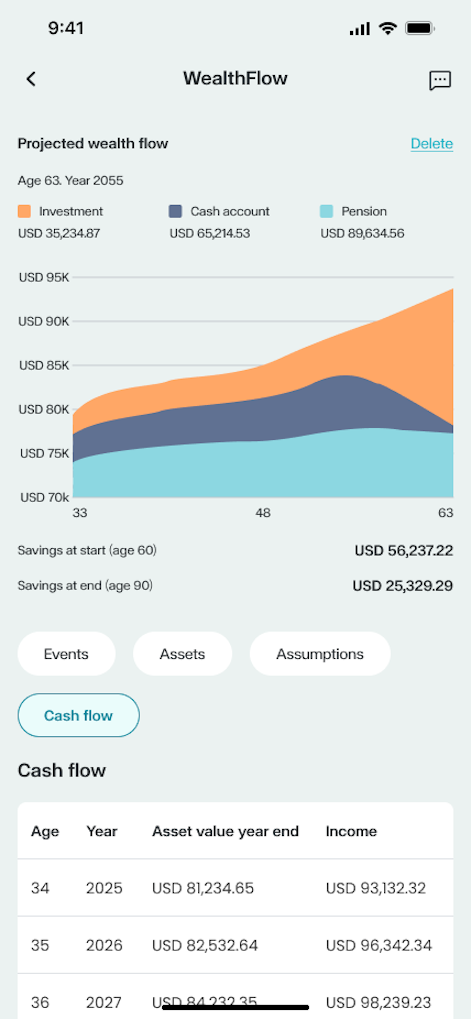
WealthFlow
Our innovative WealthFlow feature offers a holistic view of your financial health by allowing you to connect and synchronise your bank accounts and investment accounts. This integration enables seamless tracking of your finances and better financial planning.
Goal Tracking
Set and track your financial goals within the app, receiving regular updates and insights to help you stay on course.
Live Net worth Tracker
Keep an eye on your overall financial health with our live net worth tracker, which aggregates data from all your accounts to offer an up-to-date view of your net worth.
Secure Document Storage
Store important financial documents securely in the app, ensuring you have access to them whenever needed.
Alerts and Notifications
Stay informed with custom alerts and notifications on market movements, financial plan updates, and opportunities to enhance your financial strategies.
Investment Advice With a Clear Purpose
Investment decisions become more useful when they start with what the capital needs to achieve.
That means understanding your objectives, timeframe, liquidity requirements, risk profile and wider financial circumstances before deciding how money should be invested.
For internationally mobile investors, it can also mean considering how residence, currencies and existing arrangements affect the investment picture.
Hoxton Capital Management (Europe) Ltd provides investment advice within its applicable regulatory permissions, helping clients understand their options and make investment decisions based on their individual circumstances.
Financial clarity. Delivered by people, enabled by technology.
Book an Investment Advice Consultation

